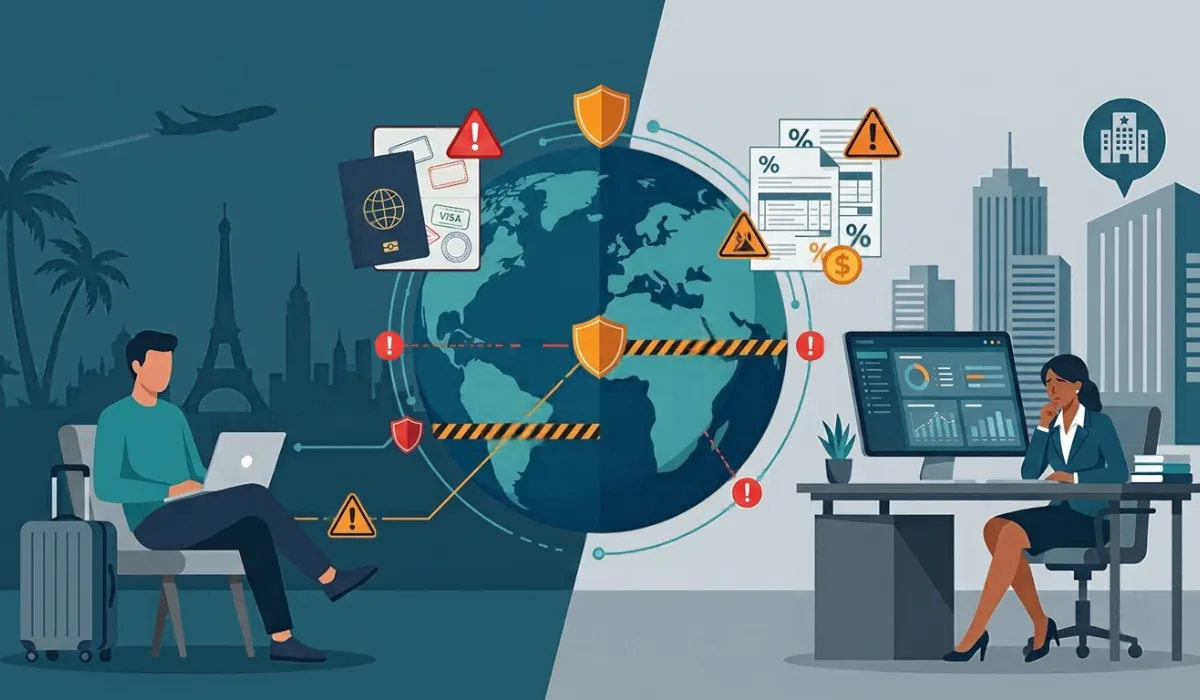
Short overseas work trips can create unexpected immigration, tax and employment obligations for employers, prompting legal and global mobility advisers to call for stronger oversight of international remote work.
As hybrid working expands, some employees are combining business travel with extended periods of working abroad. For HR teams, the challenge is no longer limited to approving conference attendance. Employees may spend several weeks overseas while continuing to work for their home-country employer, access company systems and serve clients remotely.
According to employment law adviser LegalVision and global mobility specialist Vialto, these arrangements can raise questions about work permissions, local employment laws, payroll, taxation, insurance and data security.
The central message for HR teams is clear: overseas work should be assessed separately from ordinary remote working, with approval based on the destination, duration and activities involved.
Why Short Overseas Trips Can Create Compliance Risks
A short stay does not automatically mean an employee can legally perform their planned work.
Some countries allow business visitors to attend meetings, conferences or training but restrict productive work or certain client-facing activities. The permitted activities depend on the destination's immigration rules and the individual's circumstances.
Employers also need to consider employment protections. An Australian-based employee may retain certain Australian workplace entitlements while working overseas, and local employment laws may also apply. The Fair Work Ombudsman advises employers to assess these arrangements based on the relevant circumstances rather than assume that working abroad removes Australian obligations.
For HR, this means an overseas trip should not be approved solely because a manager considers it brief or work can be completed remotely.
How Frequent Travel Can Create Tax Exposure
Tax obligations can arise through repeated trips, even when employees do not relocate permanently.
Hong Kong provides one example. Under its salaries tax rules, qualifying visitors who render services in Hong Kong for no more than 60 days during a year of assessment may be exempt from salaries tax, subject to the applicable conditions. The Inland Revenue Department explains that the calculation and treatment depend on the circumstances, so employers should not treat the threshold as a universal safe harbour.
Without centralised travel records, several separate visits can push an employee beyond a relevant threshold or create reporting obligations that the employer did not anticipate.
There may also be implications for the organisation itself. Depending on the activities performed and the applicable tax rules, an employee who regularly negotiates contracts, generates revenue or makes significant business decisions in another country could contribute to a taxable business presence, commonly referred to as a permanent establishment.
These issues require destination-specific tax advice rather than a single global rule.
What Should an International Work Policy Cover?
A practical starting point is to require employees to obtain approval before undertaking work from another country.
That approval process should assess:
- Immigration permissions: Whether the employee's planned activities are permitted under the relevant visa or entry conditions.
- Length of stay: The number of days spent in each country, including cumulative travel across multiple visits.
- Tax and payroll: Potential individual tax liabilities, employer reporting duties, social security or superannuation obligations, and payroll implications.
- Employment law: Whether local workplace requirements apply alongside any continuing home-country entitlements.
- Insurance and safety: Whether company insurance covers the employee and whether appropriate health, safety and emergency arrangements are in place.
- Data security: Whether accessing company systems or handling confidential information from the destination creates additional security or regulatory risks.
Policies should also define which countries are permitted, set approval limits, identify who reviews higher-risk requests and allow approvals to be reconsidered if circumstances change.
Improve Travel Tracking and Accountability
A policy alone will not be effective if the organisation cannot see where employees are working.
HR teams can work with finance, payroll, legal, tax and mobility specialists to establish a central approval process and track travel through corporate booking systems or other appropriate reporting methods.
Organisations should prioritise destinations and employee groups that present greater potential exposure, such as frequent international travellers, senior decision-makers and employees undertaking client-facing or revenue-generating activities abroad.
Clear responsibilities also matter. Employees should know when they must disclose travel plans, managers should not approve exceptions informally, and specialist teams should be involved when a request crosses defined risk thresholds.
Supporting Flexibility Without Overlooking Compliance
International remote work can help organisations support employee flexibility, client relationships and global collaboration. The aim of stronger oversight is not necessarily to prevent overseas work, but to make sure it happens within the relevant legal and operational requirements.
For HR leaders, the most effective approach is to treat work-from-anywhere arrangements as a managed employment practice rather than an informal lifestyle benefit. Clear rules, early assessment and reliable travel records can help employers identify issues before they become costly compliance problems.
Because immigration, tax and employment requirements differ between countries, organisations should obtain appropriate local advice before approving arrangements that could create cross-border obligations.